Make borrowing a visible trade between immediate capacity and future repayments. Tie investments to a specific bottleneck, show their payback conditions, and let players compare a loan with slower growth. Prototype one small loan and one store upgrade before adding a full finance tree. The official source below establishes supermarket operations context only; the loan rules and investment examples here are original.
Define cash flow and repayment rules
Loans give a store access to cash now in exchange for a known future obligation. Define principal, payment timing, interest or fee, and what happens if the store has a weak week. The official Supermarket Simulator listing describes managing stock, store layout, and business growth; it establishes the supermarket-management context only. The financing model here is an original design proposal. See Nokta Games for the limited context claim.
Show the full payment schedule before the player borrows. Avoid a single vague debt meter: display the next due date, payment amount, remaining balance, and any penalty for missing a payment. Let players compare borrowing with slower growth, saving cash, or reducing orders so a loan is one option among several.
Tie investments to store bottlenecks
Tie each investment to an operational bottleneck. A refrigerated display can widen perishable stock, an extra checkout can reduce queue delays, and storage can support larger orders. State the purchase cost, recurring expense, capacity gained, and condition under which it pays off. Do not promise a fixed return if demand can vary.
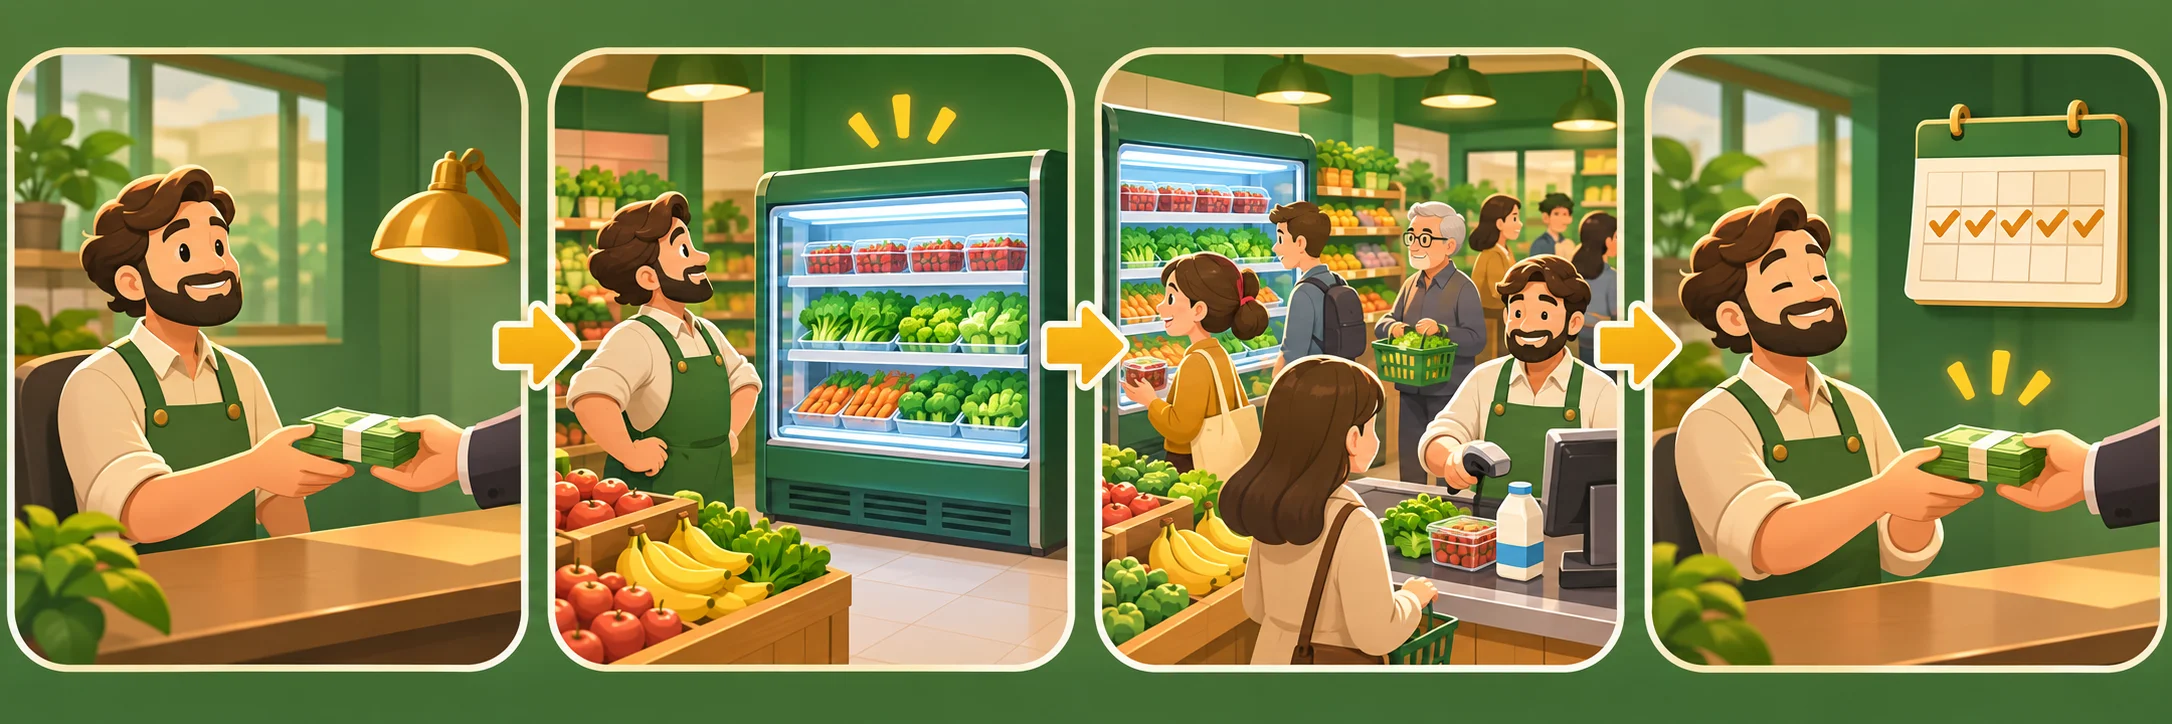
Use a short planning horizon and explain what the investment changes immediately. If expansion increases rent or staffing needs, show those costs alongside the benefit. Players should be able to identify whether the constraint is inventory, checkout throughput, or floor space before choosing what to finance.
Show risk before borrowing
Make risk legible through scenarios rather than surprise penalties. A low-demand week can leave less cash for repayment, while over-ordering can trap funds in unsold stock. Show a forecast range, keep essential operating costs visible, and offer a recovery action such as adjusting orders, delaying an optional upgrade, or selling excess inventory.
Keep loan size and investment scale bounded by the shop’s current cash flow. A small loan should not trigger a debt spiral from compounding hidden charges. Let players see how many ordinary sales periods are needed to cover the purchase under cautious and typical demand, and allow them to repay early if that fits the design.
Test downturn and payoff scenarios
Test a loan and an investment from identical starting conditions under typical demand, a sales dip, and a stock shortage. Record cash after operating costs, scheduled payment, and recovery options. Ask players to explain why the purchase was worthwhile and what they would change if revenue falls.
For related stock operations that can create investment bottlenecks, see a related guide to supermarket stock operations. Pass when players can predict the next repayment, identify the bottleneck an upgrade addresses, and recover from a weak period without losing control of the store.
FAQ
How should loans work in a supermarket simulator?
A loan should provide usable cash now and a repayment obligation players can inspect before accepting it. Show the principal, fees or interest, payment amount, due dates, remaining balance, and consequences of a missed payment. Keep the rules stable and avoid hidden compounding that can turn a reasonable purchase into an unexplained debt spiral.
What investments should improve store operations?
Investments should address specific store constraints, such as checkout throughput, storage, or refrigerated capacity. Show the upfront price, any recurring cost, the capacity change, and the demand conditions that make it useful. Let players compare upgrades with saving money or adjusting inventory before committing.
How do you show loan risk clearly?
Use visible cash-flow forecasts and stress cases, such as weak sales, unsold stock, or an unexpected operating expense. Make scheduled payments and essential costs visible, and provide recovery choices like reducing future orders or postponing an optional upgrade. Avoid surprise fees and preserve a path back to stable operations.
What should you test in a loan system?
Compare the same purchase under typical demand, a sales dip, and a stock shortage. Track cash after operating costs and payments, whether the investment removed its target bottleneck, and what recovery actions remain. Ask players to predict repayments before borrowing and explain whether they would choose a different investment after the downturn.